Connect with us

Business

Brain drain hits Nigerian banks as tech experts, others resign in droves

Published

on

Spread the love
In the last three weeks, bank customers across the country have had cause to complain about poor services by lenders, especially with regard to tech application delays and outright failure.

Funds transfer between bank customers, in some cases now take an upward of two weeks to either drop in the receiver’s account or reversed to the sender.

Besides this obvious development, information is rife that most of the banks are working round the clock to manage internal tech problems that have suddenly hit them due to mass resignation of tech experts, who are travelling out of the country for greener pastures.

Besides the current wave of managing the crisis, the fear of succession has also gripped some of the establishments as the old hands are likely to end up not having anyone to take over from them. Fears that the quality of service provided by the banks in the country might even worsen in the coming months are growing.

Indeed, industry sources believe that banks are set to be hit by a great wave of resignations in September as a lot of their employees are booked to obtain their visas by the end of this month. At the post-Bankers’ Committee meeting press briefing held in April, the Chief Executive Officer of Sterling Bank Plc, Abubakar Suleiman, told reporters that the industry had been hit by an exodus of tech talents.

Maduka College Advert

“So many of our very experienced talents, especially in the area of software engineering, are either leaving the industry or leaving the country,” a development he referred to as a “great resignation,” he said.

Suleiman stated that the Chartered Institute of Bankers of  Nigeria (CIBN), the umbrella professional body for lenders in the country, would “drive the process of training more skills in the area where we see deficits,” adding that the bank CEOs at the meeting discussed plans to fund training for new tech-focused staffers to replace those who have left.

There have been reports on social media in recent times that Nigerian banks are facing frequent system breakdown and other IT related challenges as most of their tech engineers have resigned to join digital firms in the country’s booming fintech sector, especially the global conglomerate, Amazon, which began operations in Nigeria’s e-commerce space a few months ago.

It was however gathered that it was not only tech focused staff of the banks who are quitting in order to take up juicy appointments both within and outside the country.

An Assistant Head of Operations at the branch of a Tier 1 bank, who spoke on condition of anonymity, told New Telegraph’s correspondent that he recently obtained his visa to pursue a Masters Degree programme in the United Kingdom and would be leaving the country with his family next month.

According to him, he decided to apply for the visa, following encouragement from several former colleagues who resigned in the last few months and have secured jobs or admissions for post graduate programmes either in Europe or Canada.

The bank official said: “Despite the fact that the tough economy in Nigeria has been leading many bank staff in the last seven years to resign to seek better opportunities outside the country, I was not too keen on making that move.

“However, as economic conditions and insecurity have worsened since early this year, my wife and I decided that I should try my luck and apply for a UK visa. I was pleasantly surprised to be informed that my application was successful,” he said.

He disclosed that his immediate superior, the Head of Operations at the branch, had also obtained a UK visa and would be submitting his resignation letter in the coming days.

“The situation (wave of resignations in the industry) is really very serious and I’m wondering how banks are going to cope in terms of service delivery, if it continues. I can tell you that out of every 10 bank employees that you speak with today, at least four will tell you that they are making serious plans to “japa” (local parlance for leaving the country for greener pastures abroad).

“A lot of my colleagues are already complaining of being overworked because staff who resigned months ago are yet to be replaced,” he said.

Downturn in economy Another middle level bank staff at a Tier I bank branch in Lagos, who echoed similar views, predicted that the wave of resignations would increase in the coming months as economic conditions and governance issues in the country continue to deteriorate ahead of the general election next year.

“A lot of people are trying to ‘japa’ due to the situation in the country. The naira is heading towards N1, 000 per dollar; the prices of goods and services (inflation) are accelerating at an alarming rate; students of government-owned higher institutions have been at home for over six months now because of the strike embarked upon by their teachers and the rising wave of killings and kidnapping cases across the nation, are making many people to believe that with the election next year drawing near, governance will completely collapse. Thus, the only option left for any serious person is to travel abroad.”

The bank official revealed that in a bid to tackle the crisis, the financial institution she works for had reduced the minimum academic qualification required for people applying for permanent staff positions to Second Class Lower (2/2) University Degree from Second Class Upper (2/1).

She, however, said that the lowering of the academic qualification did not appear to be stemming the wave of resignations as many of the young permanent staff employed by the bank in recent times has quit after only two years to accept better offers outside the industry.

“Most of the young people that are even lucky to be employed as permanent staff by banks are not even interested in spending more than three or four years in the industry. After about two years, you will hear that they have either migrated to Canada or are doing remote work,” she said.

The bank official debunked the view that increasing automation would mitigate the impact of the resignations on the quality of service provided by the banks. She argued that while most bank operations are automated, there are still services that require the human element, pointing out that a lot of bank customers in the country prefer to visit bank branches to resolve issues that could have been addressed from the comfort of their homes.

Commenting on the wave of resignations and its likely impact on the industry, the President of the Bank Customers Association of Nigeria (BCAN), Dr Uju Ogubunka, told New Telegraph that “the impact is already being felt. Many experienced and skilled bankers are already resigning for greener pastures abroad. It is a reality.”

According to him, the resignations will adversely impact the industry as “service quality will go down and people will complain and all that.”

Ogubunka, who noted that the wave of resignations was not peculiar to the banking industry, said that he knew a lot of people in other sectors of the economy who are also planning to quit their jobs to look for better employment offers outside the country. He attributed the development to the tough economy, pointing out that it was in the nature of human beings to emigrate in search of a better life.

“That is why we are asking that it is very important that all the focus should be on improving the Nigerian economy,” he stated.

On his part, the CEO of BIC Consulting Services, Dr Boniface Chizea, said that he could not predict to what level the great resignation will get to before it would start to impact the banks negatively. He noted that while automation is helping the banks to cope with the resignation of key staff, the industry would be concerned if the number of exiting staff continues to head north.

Chizea said: “There are countries out there, like Canada, that have labour shortage. So, people will want to move to such places to search for work. That is why we must tackle our economic problems.

What is causing the high inflation; the depreciation of the naira?” Blessing in disguise Last week, in his address at the pre-media briefing for the CIBN’s 15th Annual Banking and Finance Conference (ABFC), scheduled for September 13 – 14, Suleiman, who is the Chairman of the Consultative Committee of the conference, announced that an ongoing research finding on, “Analysis of Human Capital Attrition in a Global Context: A Case Study of the Financial Services Industry,” would be shared for information of stakeholders and value addition to the 15th ABFC.

Responding to a question on what measures the banking industry is taking to address the great resignation, he said: “With reference to the Chinese word for crisis, which also means opportunity, our attitude is that Nigeria is not lacking in healthy, young people, who are willing and are able to work. Therefore, if we see ourselves losing talent, the best response is to actually focus on converting those young people as replacement for those who are leaving.”

He further disclosed that “the industry, as a collective, is putting together a plan that will enable us support individuals who are looking to acquire skills in the area of technology and all other fields where we have skills shortage. The thinking is that actually, we can turn the crisis into an opportunity.”  (New Telegraph)
Business

Binance Halts Withdrawals After Reported $6.3bn Crypto Hack

Published

on

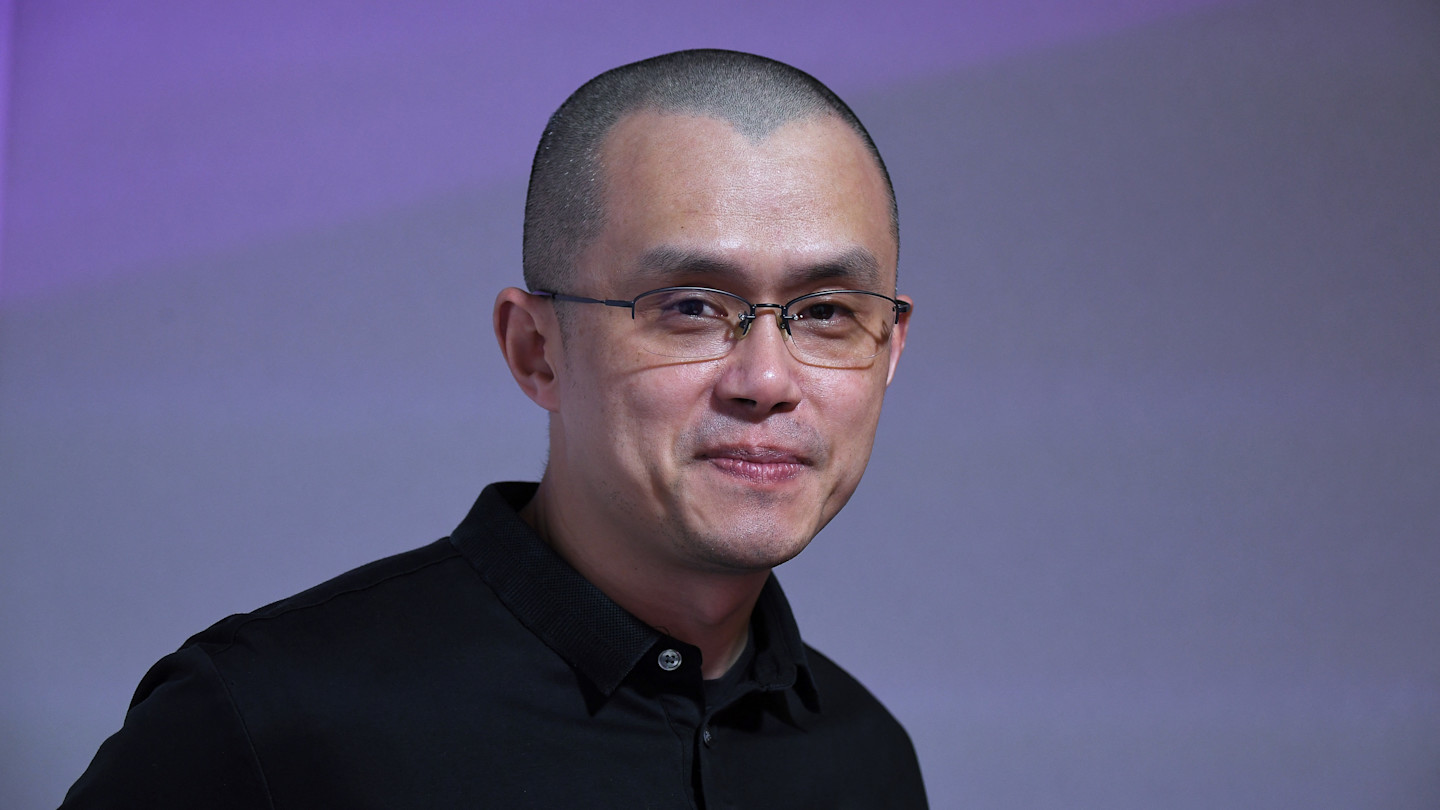
Founder Changpeng Zhao told customers their ‘funds are safe!’ after a cyber attack on the crypto exchange © Eric Piermont/AFP
Spread the love

Binance, the world’s largest cryptocurrency exchange, has temporarily suspended deposits and withdrawals following a major security breach reportedly involving about $6.3 billion in digital assets.

The exchange said its preliminary investigation indicated that an attacker may have gained unauthorised access to its systems through a compromised laptop belonging to an engineer.

In a statement released on Thursday, Binance disclosed that it was working with blockchain intelligence firms, cryptocurrency issuers and law enforcement agencies to investigate the incident and recover the affected assets.

Maduka College Advert

“The estimated total impact sits at around $6.3B. We have worked with blockchain partners to freeze affected assets, with $3 billion frozen on-chain so far,” the company said.

Binance explained that its initial findings suggested the attacker had compromised a DevOps engineer’s laptop, potentially enabling access to a service container through which unauthorised withdrawal transactions were submitted.

However, the exchange said it had found no evidence that private keys, which provide access to cryptocurrency wallets, had been exposed.

The company subsequently suspended deposits and withdrawals while its security team conducted checks and worked to contain the incident.

“Our teams are aware of reports of a potential security issue and are actively investigating. User funds are completely safe,” Binance said in a post on X.

North Korean Hackers Suspected

Blockchain intelligence firm TRM Labs has linked the incident to TraderTraitor, a cybercrime operation associated with North Korean hackers.

If the reported losses are confirmed, the incident would rank as the largest cryptocurrency theft on record, surpassing the $1.5 billion cryptocurrency theft from the Bybit exchange in 2025, which was attributed to North Korean hackers.

However, investigations into the Binance incident are ongoing, and the full circumstances surrounding the attack have yet to be conclusively established.

The incident has renewed concerns about the vulnerability of cryptocurrency platforms to cyberattacks, particularly those involving compromised employee devices and unauthorised access to internal systems.

Tether, Circle Freeze Funds

Major cryptocurrency companies have moved to limit the potential losses by freezing digital assets believed to be connected to the incident.

Tether Chief Executive Officer Paolo Ardoino said the company had frozen approximately $1.5 billion in USDT, its dollar-linked stablecoin.

Circle, the issuer of another major stablecoin, also reportedly froze about $800 million in assets amid reports of a potential security breach at Binance.

Binance said the amount of frozen funds could increase as investigators and industry partners continue tracing transactions across different blockchain networks.

The exchange is working with relevant stakeholders to identify the movement of the affected assets and prevent further transfers where possible.

Bitcoin, BNB Prices Fall

The reported security breach triggered a negative reaction in the cryptocurrency market, with major digital assets recording significant declines.

Bitcoin fell by approximately four per cent to $77,229 in the hours following reports of the incident.

BNB, the native token of the blockchain ecosystem developed by Binance, also dropped by about 7.5 per cent.

The price movements reflect investor concerns about the potential consequences of a major security incident at a leading cryptocurrency exchange.

Binance, which was established in 2017, reportedly holds approximately $140 billion in digital assets, making its security arrangements and ability to protect customer funds significant to the wider cryptocurrency industry.

CZ Says Customer Funds Should Be Covered

Binance co-founder and former chief executive, Changpeng Zhao, popularly known as CZ, also commented on the incident.

Although he stepped down from management of the exchange in 2023 following a settlement with United States authorities over anti-money-laundering compliance failures, Zhao said he expected customer funds to be protected.

As a shareholder, he expressed confidence that users would not ultimately bear the financial losses associated with the incident.

Binance has also indicated that it would cover eligible customer losses using its own resources, including its Secure Asset Fund for Users (SAFU), an emergency fund established to provide an additional layer of protection for customers.

The company’s final assessment of the losses and the extent of customer exposure will depend on the outcome of the ongoing investigation.

Polymarket Reports Separate Security Incident

The Binance incident emerged just hours after Polymarket, a popular prediction market, reported a separate security issue involving one of its third-party service providers.

Polymarket temporarily suspended trading after discovering that the provider had been compromised, potentially exposing some users to unauthorised activity involving their accounts.

The platform said it had referred the matter to law enforcement and promised to compensate affected users.

The two incidents have raised fresh questions about the security of cryptocurrency trading platforms and the risks associated with third-party technology providers.

In recent years, cryptocurrency exchanges and decentralised finance platforms have repeatedly been targeted by hackers seeking to exploit vulnerabilities in software, digital wallets and internal security systems.

Crypto Industry Faces Growing Security Threats

The reported Binance breach comes amid continuing concerns over cryptocurrency theft and the growing sophistication of cybercriminal operations.

According to blockchain analytics firm Chainalysis, North Korean-linked hackers stole approximately $2 billion in cryptocurrency in 2025, representing a 50 per cent increase from the previous year.

In another major incident, hackers reportedly stole about $280 million from the Drift cryptocurrency exchange in April.

The latest developments have highlighted the importance of stronger cybersecurity controls, effective monitoring of employee devices, rapid detection of suspicious transactions and cooperation between cryptocurrency companies and law enforcement agencies.

For Binance, the immediate priority remains containing the incident, tracing the affected funds and establishing the full extent of the losses.

The company is expected to release a detailed technical report after completing its investigation and verifying the facts surrounding the breach.

Continue Reading

Business

Dollar to Naira exchange rate today, September 23, 2026

Published

on

Naira rebounds to 1,275/$ at parallel market
Spread the love
The Nigerian naira is trading at different rates against the United States dollar across the official Nigerian Foreign Exchange Market (NFEM) and the parallel market on Wednesday, September 23, 2026.

The latest available data show that the naira strengthened to N1,327.78 per dollar at the NFEM on Tuesday, from N1,329.80 recorded on Monday.

The latest movement represents a N2.02 appreciation by the naira against the dollar on a day-to-day basis.

In the parallel market, the dollar was quoted at about N1,389 on Tuesday, down from N1,390 recorded the previous day.

The parallel-market rate puts the gap between the official NFEM rate and the street-market selling rate at about N61.22 per dollar.

Maduka College Advert

At the parallel market rate of N1,389, customers buying $100 would need approximately N138,900, while $1,000 would cost about N1.389 million.

The exchange rate available to individuals and businesses may vary depending on the dealer, location, transaction size and prevailing market conditions.

The naira’s recent performance has come amid developments in Nigeria’s foreign exchange market, including changes in dollar liquidity and monetary policy.

The Central Bank of Nigeria has continued to monitor conditions in the foreign exchange market as the naira trades around the N1,300-per-dollar level at the official market. Reuters also reported in September that the naira had remained relatively stable, supported by central bank dollar sales and subdued import demand.

For Wednesday, September 23, the latest confirmed figures put the dollar at N1,327.78 at the NFEM and around N1,389 in the parallel market.

The rates could change during the day as demand and supply conditions shift across both markets.

Continue Reading

Business

Enugu Air Launches New Website

Published

on

Spread the love

…moves online services to www.enuguairlines.ng

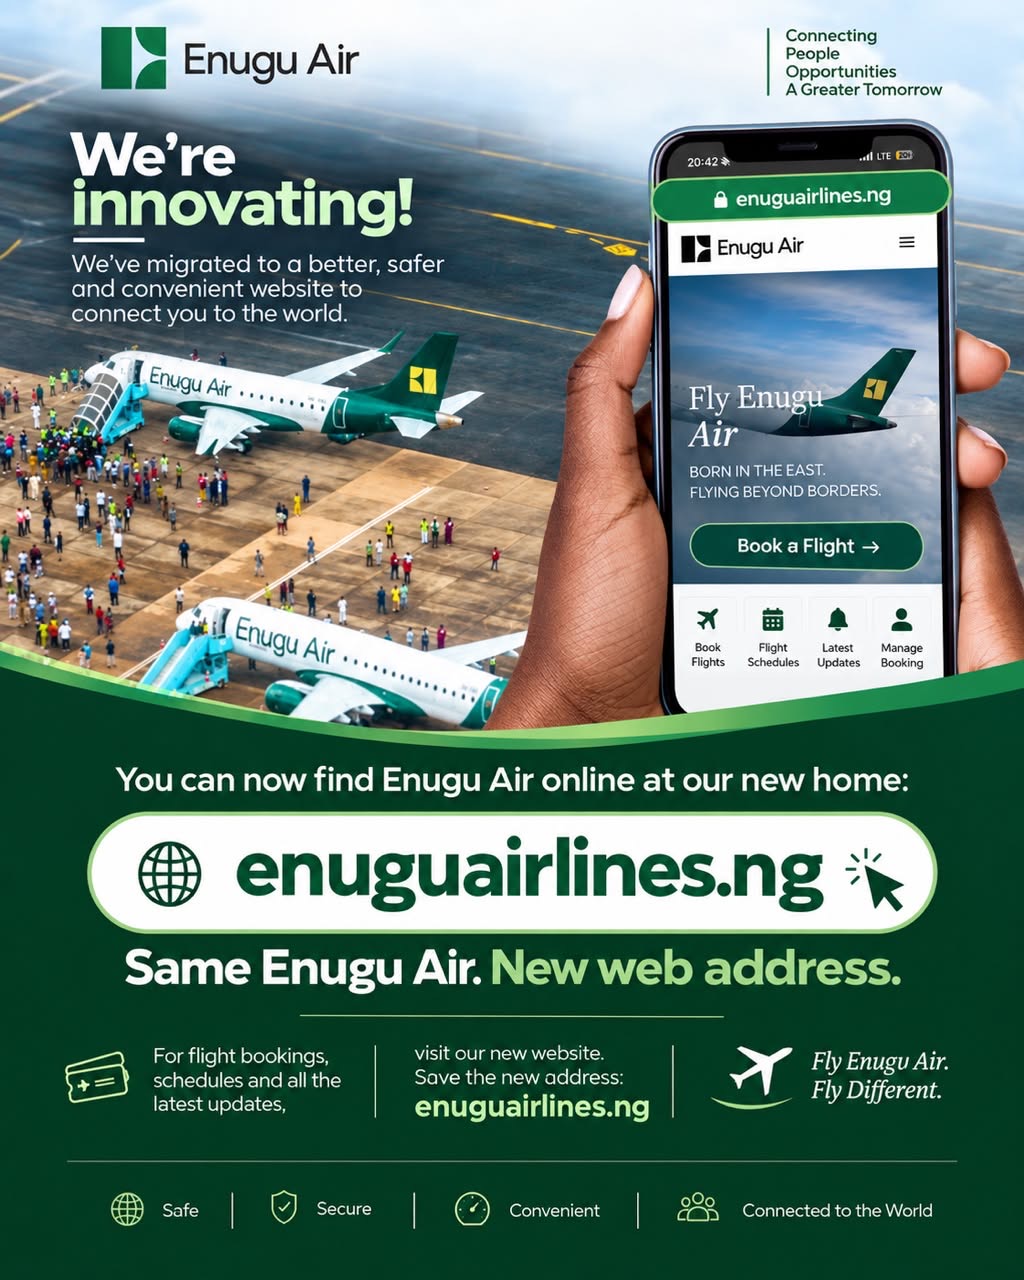
Enugu Air has announced the launch of its new official website, enuguairlines.ng, as part of efforts to provide passengers and customers with a better, safer and more convenient digital experience.

The airline said the migration to the new website is designed to improve how passengers connect with Enugu Air and access its services online, including flight bookings, schedules and the latest updates.

Announcing the development, the airline said: “We’ve moved! We’re innovating! We’ve migrated to a better, safer and convenient website to connect you to the world.”

Passengers can now access Enugu Air’s online services through its new web address, enuguairlines.ng, which the airline described as its new digital home.

Maduka College Advert

The airline urged passengers and prospective travellers to save the new web address and use it for flight bookings, checking schedules and obtaining the latest information about its operations.

“Same Enugu Air. New web address,” the airline stated, emphasising that the change represents an improvement in its digital platform while retaining the Enugu Air brand and services.

The airline further encouraged customers to visit, www.enuguairlines.ng for all flight-related information and online services.

It further stated that the old website, enuguairlines•com has been discarded and no longer in use.

Continue Reading

Trending

Maduka College Advert